Two founders can run firms with exactly the same earnings, and one firm can be worth twice as much as the other.
The difference isn't in the profit and loss statement. It's in how much of that profit a buyer believes will still be there once the founder has gone.
Who might buy or take in your firm
When founders think about selling, they often picture one buyer. In practice there are several kinds, and each looks at your firm a little differently.
- Another law firm that wants your clients, your team or your practice area, through an acquisition or a merger.
- Your own partners or senior lawyers, buying you out over time.
- Investor-backed groups. In most US states only lawyers can own a law firm, so investors usually come in through a management services organization (MSO) that runs the business side, not the legal practice itself.
The details differ, but every one of them is asking the same question: what will this firm earn without its founder, and how sure can we be?
What buyers look at
Whether clients will stay. This comes first. Are your clients loyal to the firm, or to you personally? Do they work with more than one person here? Would they stay if you left?
How the work comes in. Repeat work from established corporate clients is worth more than one-off matters. Work that arrives through the firm's name and people is worth more than work that arrives because someone recommended you.
How concentrated the clients are. If one or two clients account for a big share of your revenue, losing either would hurt badly. Buyers notice that straight away.
Whether there's a team that can lead. Is there someone besides you who can run client relationships, make decisions and develop new business? Or does everything run through one desk?
Whether the firm's knowledge is written down. Pricing, processes, client history and how things are done. If they only exist in your head, a buyer can't take them over.
How clean the numbers are. Buyers need to see what the firm really earns once your own pay and personal costs are separated out. Messy numbers mean more questions in due diligence and less confidence in the price.
Same earnings, very different value
Here's a simple illustration. These numbers are examples, not market rates. Real values depend on the firm, the buyer and the deal.
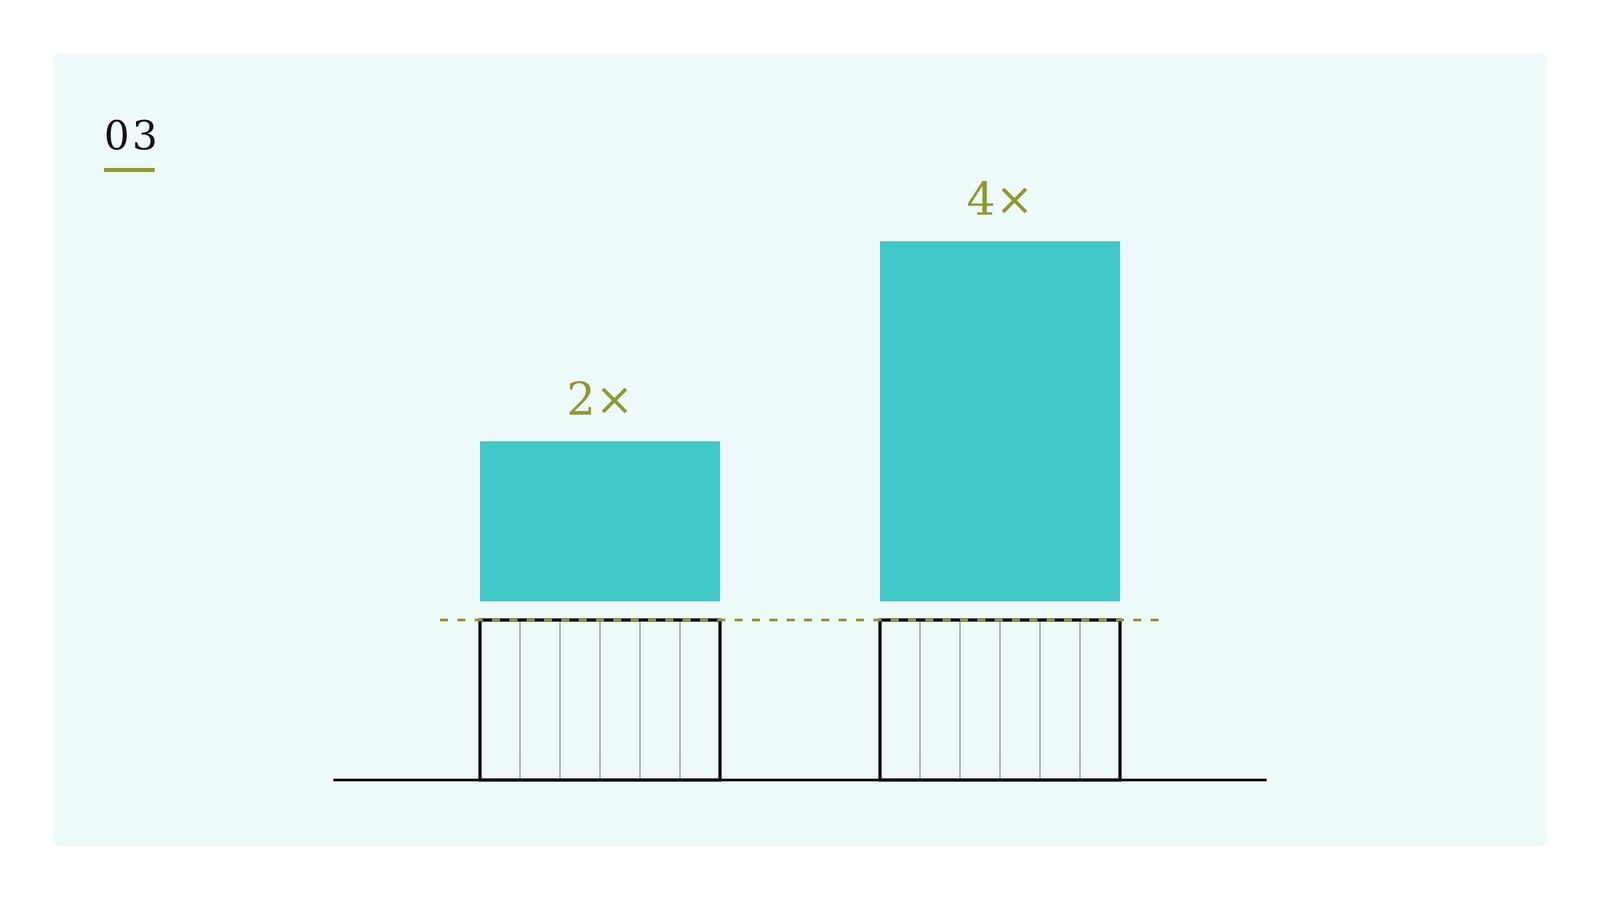
Two firms each have $800,000 a year in seller's discretionary earnings (SDE): the profit left for the owner after normal costs.
| Firm One | Firm Two | |
|---|---|---|
| Annual SDE | $800,000 | $800,000 |
| Illustrative multiple | 2× | 4× |
| Illustrative value | $1.6 million | $3.2 million |
Firm One's clients come for the founder, and most decisions wait for him. Firm Two's clients know several people in the firm, and the team runs day to day without her.
The earnings are the same. What a buyer believes about the future is not.
If a firm is taking you in rather than buying you
Mergers and combinations work the same way. The firm taking you in wants to know whether your clients will come with you and stay, whether your team will stay too, and whether the work fits what they already do.
A firm that depends less on its founder gets better terms, more say in the deal, and more firms interested in talking.
What you can change
Most of what buyers look at can be improved. Client relationships can be widened. Decisions can be shared. Knowledge can be written down. The numbers can be cleaned up.
What can't be changed quickly is the track record. A buyer wants to see that the changes have held for a while, which is why the work is best started about three years before any sale.
Where to start
The Exit Readiness Diagnostic takes four minutes. It shows where a buyer would see risk in your firm, and which gap to close first.
Find out where your firm stands.
Twelve questions, four minutes.